What does a post-dated cheque in the drawer actually protect today?
Across the UAE, building-materials distributors still take PDCs from contractors and hardware shops as security for goods sold on credit. The habit has outlasted the legal change that weakened it.
This post follows one contractor account to show where PDCs fall short, and how credit limits in 1Channel's DMS close the gap.
The same problem appears in building materials and hardware, automotive and auto components, consumer durables and electronics, and FMCG, wherever goods move on credit terms.
What Changed for Post-Dated Cheques
Since 2 January 2022, a cheque that bounces for insufficient funds has been mainly a civil matter in the UAE, not a crime.
The payee now applies to the court's execution judge instead of filing a police report. Cheques written in bad faith remain a criminal offence.
For a credit controller, that changes what a stack of PDCs is worth. It still offers a route to recover money, but a slower one.
It also no longer stops a customer from ordering beyond what the business can safely carry.
That protection now has to sit earlier, at the moment an order is placed.
One Contractor Account, Followed Through
A Sharjah distributor of tiles, sanitaryware and fittings sells to a fit-out contractor on 60-day terms. It holds three PDCs of AED 45,000 each.
The agreed credit limit is AED 150,000. Because "the cheques cover it", reps keep booking orders from the contractor's site team.
By month end the outstanding balance is AED 212,000. Then the second cheque is returned unpaid, and recovery means a court process while more goods are already out.
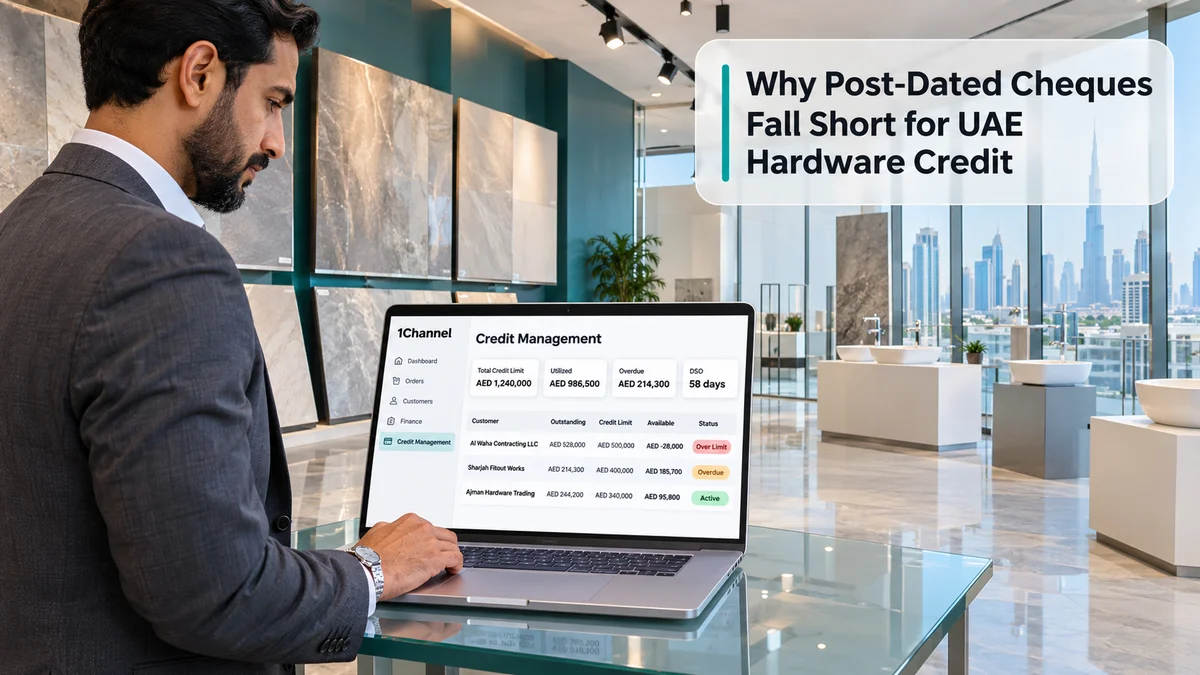
Here is what the same account looks like in the DMS Outstanding tab, where the gap shows on the day it opens rather than at month end.
| Field | What it shows for this contractor |
|---|---|
| Credit Limit | AED 150,000 |
| Outstanding | AED 212,000 |
| Overdue | AED 67,000 |
| Available | AED 0 |
| Status | Over Limit |
Putting the Check Where the Order Is Placed
In 1Channel's DMS, every customer carries its own credit limit. Credit Management shows Total Credit Limit, Utilised Credit, Total Overdue, DSO and the number of customers On Hold.
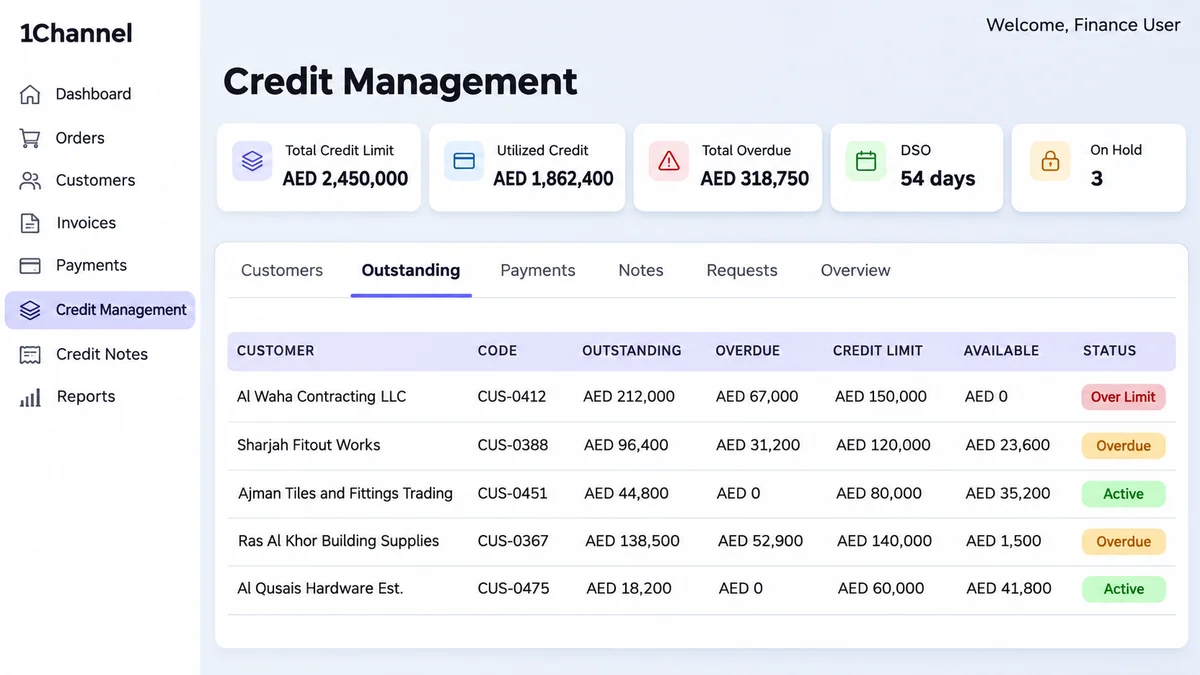
When an order would exceed the available limit, the field rep is flagged.
A manager then reviews it and, if the case is sound, raises the limit on the spot.
Pending limit changes wait in the Requests tab, and the ready reports include a Credit Override Audit Report and an Overdue Aging report for the finance team.
Order auto-validation in the AI-Powered DMS also checks stock, AED pricing, schemes and credit before an order moves forward.
That way a credit breach is caught before it reaches the warehouse.
What the Rep Sees at the Counter
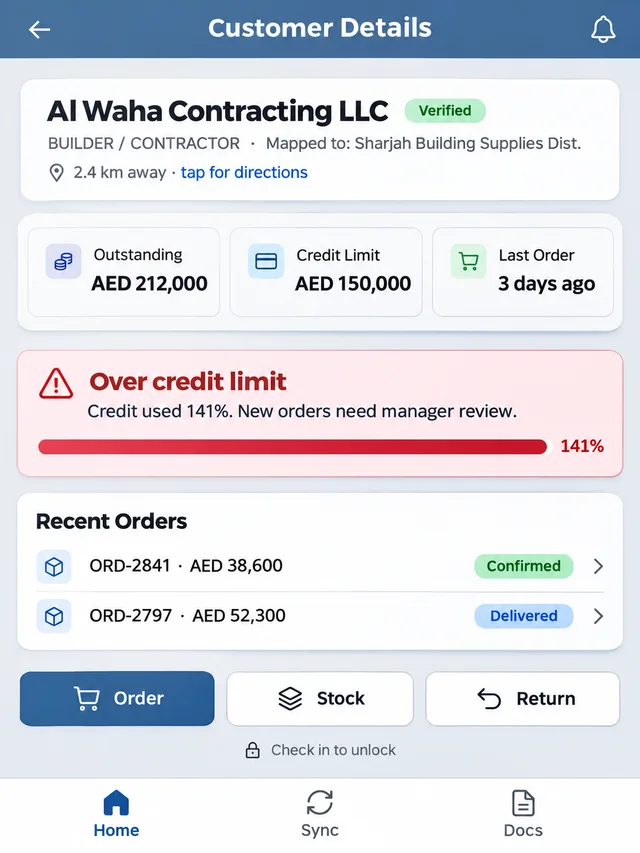
On the mobile app, each outlet card shows Outstanding and Credit % used, and the customer screen shows Outstanding, Credit Limit and Last Order tiles.
The rep visiting the contractor's site office can see the account is over limit before writing a single line.
So the conversation starts with payment, not a new order.
A second example: a new hardware shop in Ajman places its first order before any limit is set, which the system allows.
From the second order on, nothing further goes through until a credit limit is set and the earlier outstanding is cleared.
The shop never builds up exposure on trust alone.
Where PDCs Still Fit
None of this means refusing cheques. Many contractors still pay by PDC, and that is a normal payment term.
The difference is that the cheque becomes a payment record, not the credit decision.
When it is received, Record Payment logs the amount, mode and reference number and allocates it across outstanding orders.
DSO and the Overdue Aging report then show which accounts pay late, so limits can be tightened for slow payers before the next large site order.
How 1Channel Puts the Credit Check Before the Cheque
1Channel ties each trade account's limit, outstanding and overdue balance to the order itself, on the web portal and in the field app.
Finance sets the rule once, and every rep and distributor works to it on every order.
Let the Limit Decide, Not the Cheque Drawer
See how 1Channel tracks credit limits, outstanding balances and payments for every trade account in AED.
Explore Payment and Credit Management →Conclusion
A post-dated cheque still has a place in UAE trade credit, but since 2022 it is a recovery tool, not a brake on ordering.
Distributors that set a limit per account and check it on every order catch the over-limit contractor on the day it happens, while the exposure is still small.
Note: Software screens may vary based on your business structure and configured workflows.